FIVE EXPERTS · MARKET WHITE PAPER
The Chicago Acquisition Market
Owner-operated companies, the succession wave, and the quiet market · September 2026
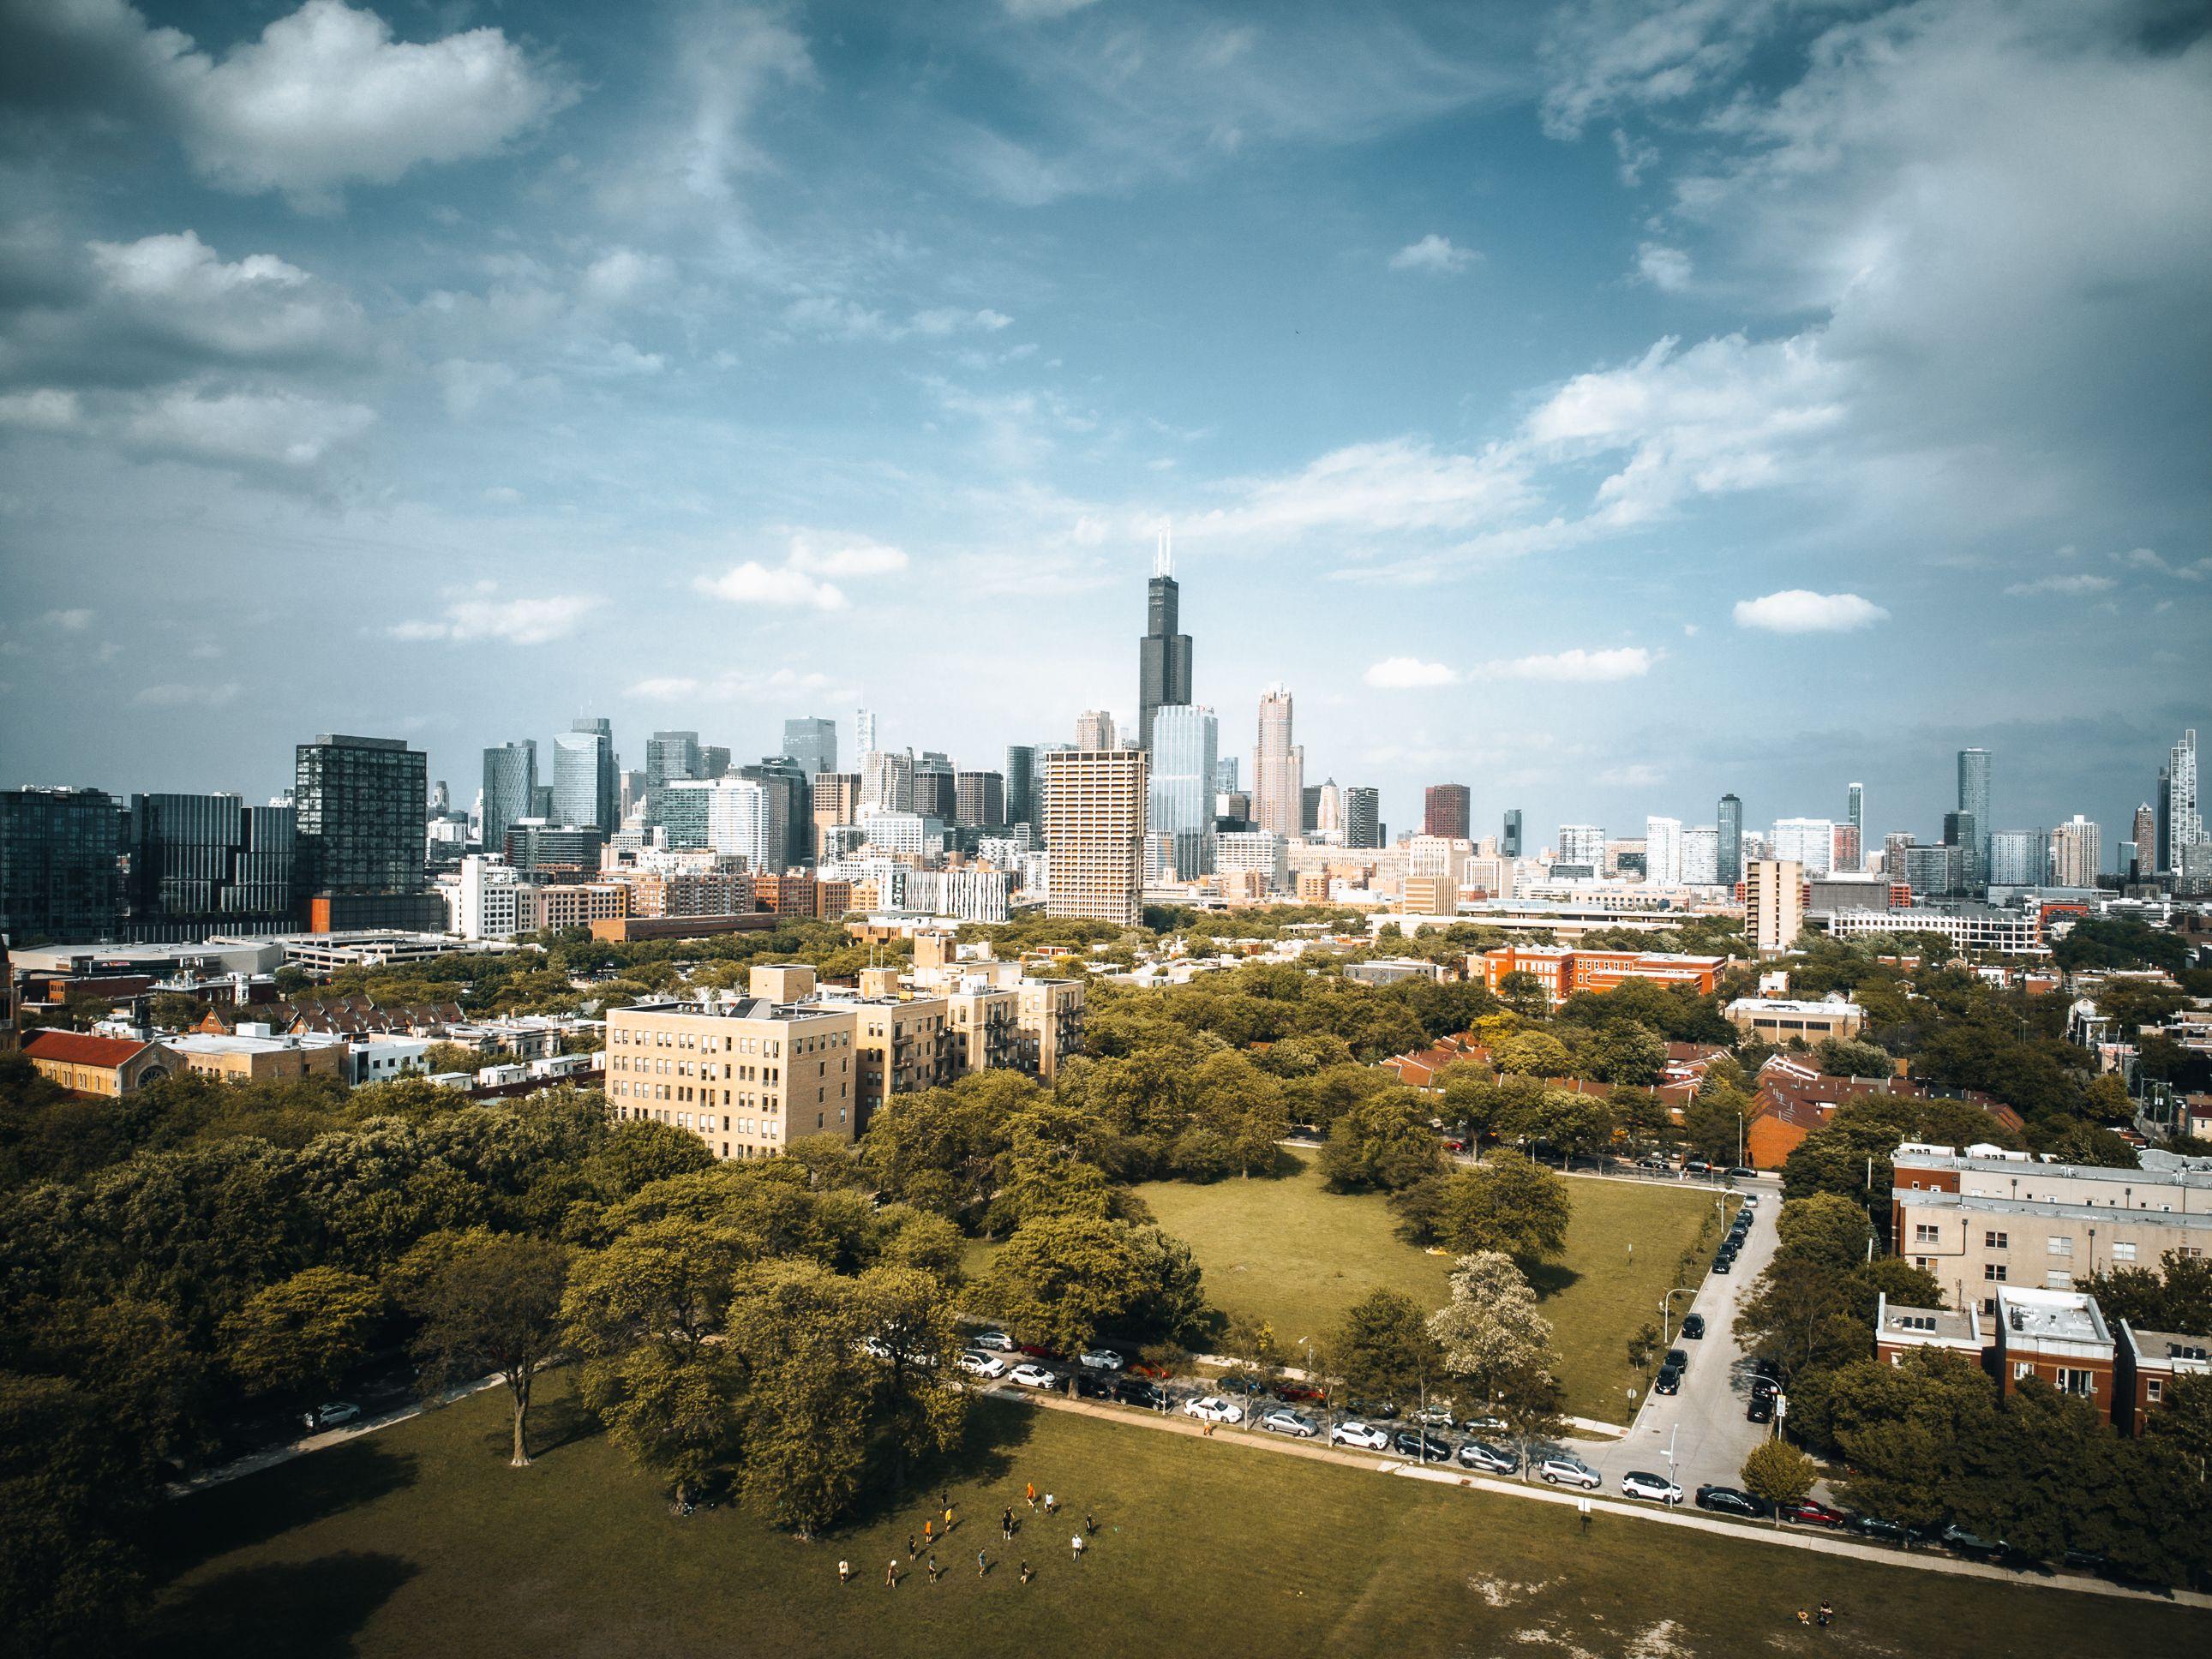
Chicago may be the most underrated acquisition market in America, and it is underrated for a strange reason: the city is so central to the world of buying small companies that everyone looks past it. One of the largest annual gatherings in entrepreneurship through acquisition happens here. Two of the business schools that mint the most searchers sit here. And a striking share of those searchers fly somewhere else to buy, while one of the deepest benches of owner-operated companies in the country ages quietly around them.
This white paper lays out what the Chicago market actually looks like for a buyer of an owner-operated company: the counted numbers, the shape of the industrial base, the succession wave as it stands here specifically, the gap between the listed market and the real one, and how the financing landscape supports acquisitions at this scale. A method note at the end says which figures come from which sources and how each class of number should be read.
The market at a glance
Figures are the latest available from each source; the method note on the final page describes how each class of number should be read.
The shape of the economy
Illinois passed $1 trillion in annual GDP, and the number that matters more than the size is the spread: no single industry produces more than about 13 percent of it, which makes greater Chicago one of the most diversified major economies in the country. For a buyer, diversification is not an abstraction. It means the metro does not live or die with one sector's cycle, and it means the universe of buyable companies spreads across dozens of categories instead of crowding into three.
The base of that economy is industrial in a way coastal metros stopped being decades ago. Manufacturing remains the state's largest major industry at roughly $132 billion in output a year, and regional analysis by the Chicago Metropolitan Agency for Planning puts traded-cluster employment at 1.4 million workers, about 37 percent of all regional jobs. Inside that: a metalworking cluster that still employs nearly twice the national average concentration of workers, a food processing cluster that has grown output by billions while others shrank, a transportation and logistics cluster growing ahead of the national average because Chicago remains the freight hub of North America, and business services as the region's single largest traded cluster. Around the manufacturers sits everything a freight capital accumulates over a century: distribution, wholesale, industrial services, and the dense layer of B2B service firms that keep all of it running.
Nationally, 87 percent of manufacturing establishments have fewer than 50 employees. The industrial economy is overwhelmingly a small-company economy, and Chicago holds one of the largest concentrations of exactly those companies anywhere in the country.
The succession wave, here specifically
The national numbers first, because they set the scale. More than half of American small-business owners are now over 55, up from roughly 30 percent in 2002, and one in four is 65 or older. Research by the McKinsey Institute for Economic Mobility projects that about 6 million small businesses will change ownership or close by 2035, with as much as $5 trillion in enterprise value at stake. And the single most important statistic in this paper is what currently happens when owners exit: in the most recent measured year, 92 percent of exits were closures. Only 5 percent were sales. The default ending for an American small business is not a handover. It is a disappearance.
Chicago's version of this is sharper than the national picture. The Great Cities Institute at the University of Illinois Chicago studied the region's family-owned manufacturers and found 61 percent facing immediate succession risk: no defined ownership plan and no identified successor. These are disproportionately the companies described above, decades old, under 50 employees, profitable, and invisible. The city's own economic development arm has stood up a family business succession program, which tells you the people closest to the data consider the handover a civic issue, not a niche one.
Every at-risk company resolves one of three ways: it passes to a successor, it sells to a buyer, or it quietly closes and its customers scatter. The 92 percent statistic says which way the tide runs when no buyer shows up. Buyers are the difference between the second ending and the third far more often than any dataset will show, because a company that closes without ever listing never appears in anyone's numbers.
The listed market and the quiet market
At the time of writing, the largest business-for-sale marketplace shows about 1,300 listings for the entire state of Illinois, most of them in the Chicago metro, and the mix is what listing marketplaces always hold: restaurants, bars, retail storefronts, salons, laundromats, franchises, and a thin layer of larger operations. Other marketplaces and brokers' own sites list businesses that never appear there, so take the most generous view: assume every listing venue combined, with no overlap at all, puts a few thousand Illinois businesses on the market at any moment.
Set even that generous number against roughly a quarter million employer firms in the state and the conclusion counts itself: fewer than two employer firms in a hundred are listed for sale, and the listed market is a rounding error on the real one. The companies most buyers actually want, the thirty-year machine shop, the industrial services firm with two decades of plant contracts, the distributor whose customers reorder monthly, are almost never in that pile. They change hands the way they always have, through a direct conversation with a buyer who showed up right, or they do not change hands at all.
A caveat any buyer working from databases should carry into this market: in Five Experts' hand-checking of more than 25,000 companies nationally, only 1 in 4 to 1 in 5 proved to be what it appeared to be. The rest were subsidiaries wearing independent names, companies that quietly sold years ago, broker listings dressed as operating companies, and businesses that existed mainly as websites. The rate has held across every industry and region measured, and there is no reason to believe Chicago is an exception. Whatever universe a buyer builds here, the true one is a fraction of the raw one.
The financing landscape
Acquisitions at this scale run on SBA lending, and Illinois has unusual depth in it. From fiscal 2020 through late 2025, SBA records show 12,451 7(a) loans totaling $6.55 billion approved for Illinois businesses, an average of roughly $526,000 per loan. The lender bench matters as much as the volume: Huntington National Bank alone made nearly 3,000 of those loans, and Byline Bank, an Illinois lender repeatedly recognized as the state's most active, wrote over $755 million across 615 loans, an average approaching $1.2 million, which is acquisition-sized lending. A buyer financing a Chicago acquisition is working in one of the most practiced SBA markets in the country, with lenders who have seen these exact categories before.
The standard structure at this scale pairs an SBA 7(a) loan with a seller note and buyer equity, and the practical ceiling of SBA lending keeps most transactions below roughly $10 million in price, which maps almost exactly onto the owner-operated companies this paper describes.
Where buyers crowd, and where it is quiet
The crowding in Chicago follows the national script: the categories with the most acquisition podcasts get the most acquisition mail. Home services, HVAC and plumbing, landscaping, managed IT. Owners in those categories now receive so much automated outreach that the mail has become wallpaper, and response rates show it.
The quiet, in Chicago specifically, is industrial. Specialty and niche manufacturing, industrial and facilities services, distribution and logistics services, food processing, commercial B2B services: the categories that require a buyer to understand what a company actually does before writing to its owner. Fewer buyers do that work, which is precisely why it works. The metro's depth changes search strategy in one more way worth naming: Chicago rewards specific theses. A buyer hunting B2B services in Chicagoland broadly is competing with everyone. A buyer hunting a defined niche inside this industrial base is often competing with no one.
What the numbers mean for buyers
Three implications follow from the data. First, the opportunity here is off-market by arithmetic, not by philosophy: with at most a few thousand listings across every venue against a quarter million employer firms, any thorough search of this metro is mostly a search of companies that will never list. Second, specificity is the scarce advantage. In a market this deep and this diversified, a broadly defined search competes with every other buyer reading the same feeds, while a precisely defined one often competes with no one. Third, the succession numbers are a clock, not a backdrop. When 61 percent of the region's family-owned manufacturers have no plan and no successor, and the national default outcome is closure rather than sale, the companies available to a prepared buyer this decade will not all still exist for an unprepared one next decade.
Method and sources
Three classes of numbers appear in this paper and they should be read differently. Public-record numbers are counted by the named sources: the SBA Office of Advocacy 2025 Illinois profile, Bureau of Economic Analysis state GDP data, the Chicago Metropolitan Agency for Planning's traded clusters analysis, the Great Cities Institute at the University of Illinois Chicago, the McKinsey Institute for Economic Mobility's ownership transfer research with 2025 Gallup survey data, SBA 7(a) lending records through late 2025, and a listing marketplace count taken in September 2026. One measured figure, the 1 in 4 to 1 in 5 rate, comes from Five Experts' own hand-checking of more than 25,000 companies nationally. Everything else is a working estimate stated in ranges. Verified numbers for any specific company come from checking that company, never from a database.
Published by Five Experts. We are not a business broker and not an M&A advisor. This paper is general information, not advice.
Stephanie Quay · Founder, Five Experts · fiveexperts.com